Mining companies rarely get much credit for moving equipment from one corporate box to another. But Aura Minerals Inc.’s agreement to acquire Newco puts a more consequential question on the table: can direct control of the mining fleet improve the economics and execution of three important assets?
Announced October 2, 2026, the transaction would bring fleet ownership, related equipment leases and dedicated heavy-equipment operations in-house across Apoena, Almas and Borborema. For investors tracking Aura Minerals through its Nasdaq listing under $AUGO, the deal is less about corporate structure than the operating leverage it may create—or fail to create.
A shift from contracted capability to owned infrastructure
Under the definitive agreement, Newco will hold the mining fleet, related equipment leases and dedicated operations serving the three sites. Aura Minerals would acquire the company, shifting fleet ownership and heavy-equipment operations inside the broader business.
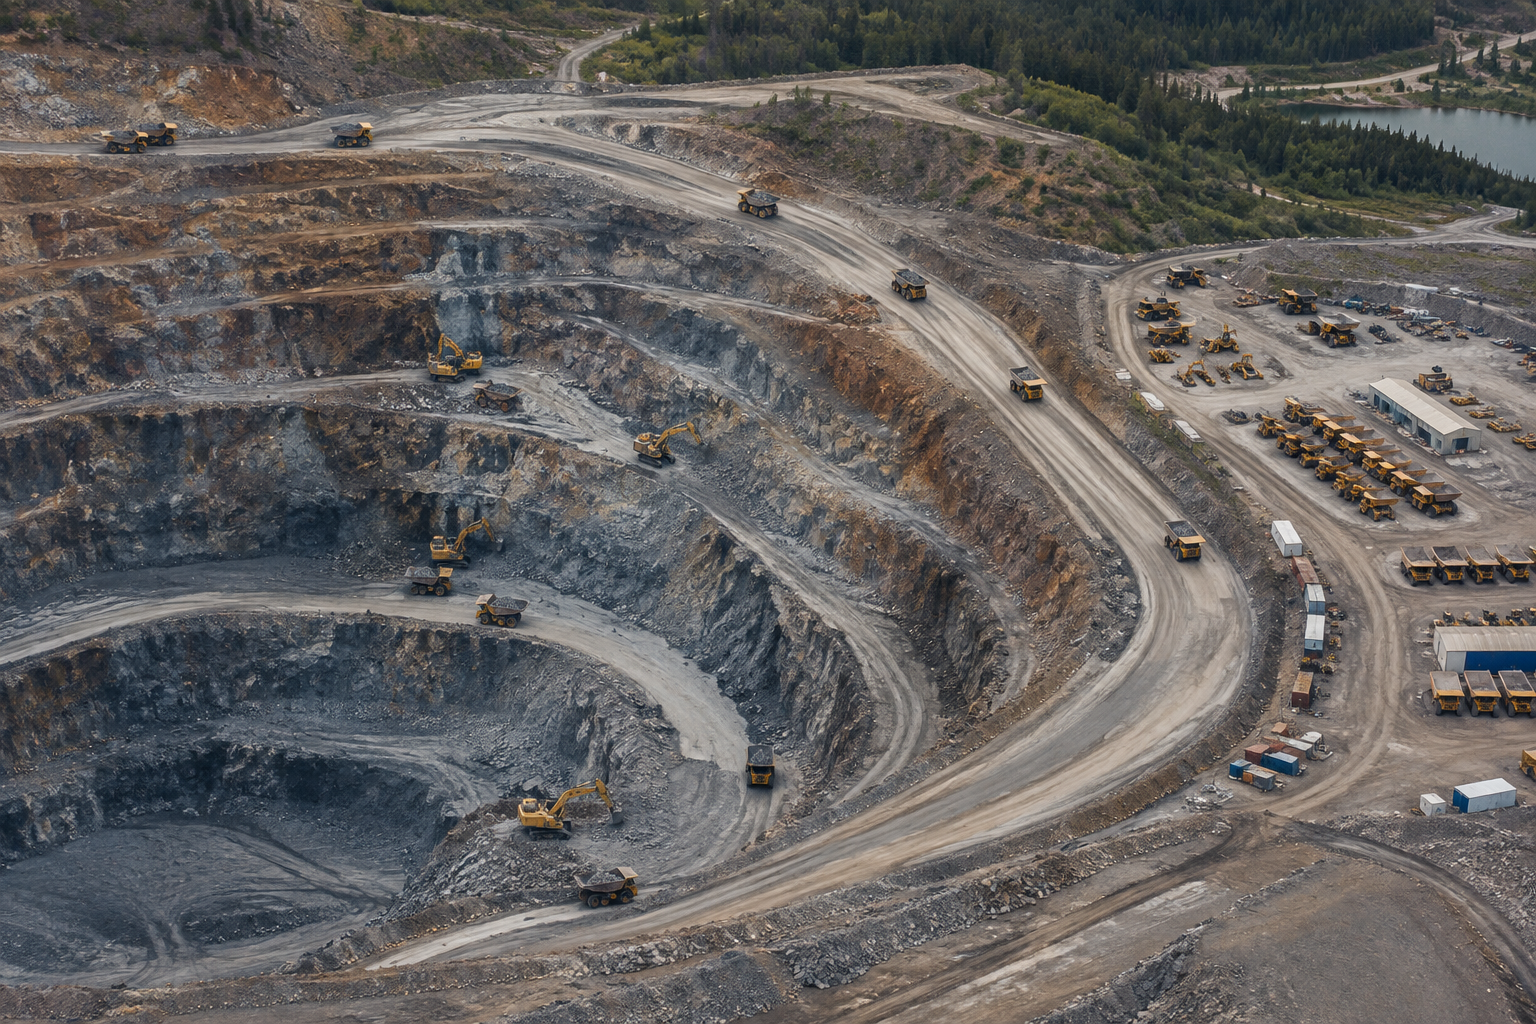
That matters because mining fleets sit close to the operating core. Equipment availability, maintenance coordination and deployment can influence how efficiently material is moved and how consistently mine plans are executed. Bringing those functions in-house may give Aura greater control over the assets supporting Apoena, Almas and Borborema.
The reported facts stop there. The announcement does not provide a transaction value, financing terms, projected savings or an expected closing date. Those omissions are not minor details; they are the numbers that will ultimately determine how investors assess the transaction.
Why operating leverage is the market’s likely focus
The potential appeal is straightforward. If internal ownership allows Aura to coordinate equipment more effectively, reduce external operating dependencies or improve utilization across its three assets, the structure could support stronger margins over time. It could also give management more direct control over maintenance planning, fleet deployment and operational scheduling.
That is the bullish interpretation—but it remains an interpretation, not a disclosed forecast. Owning equipment also brings responsibility for capital requirements, maintenance, staffing and execution. The financial outcome may depend on how efficiently the fleet is used and whether the internal operation performs better than the arrangement it replaces.
In other words, the deal may increase operating control while also placing more operational accountability on Aura. The potential for greater leverage cuts both ways: fixed or committed operating resources can become more valuable when utilization is strong, but less flexible when mine plans or production conditions change.
Three assets, one operating thesis
The common thread is that the transaction spans Apoena, Almas and Borborema rather than a single site. That gives the move a broader strategic footprint. A fleet platform serving multiple producing or development assets could provide scope for coordination, although the announcement does not quantify the expected benefits or explain how equipment will be allocated among the sites.
For US investors following $AUGO, the key issue is whether future disclosures translate this structural change into measurable operating results. Investors tracking Aura’s dual listing through B3: $AURA33 face the same question: what will the in-house model mean for costs, margins and future free cash flow?
The appropriate conclusion today is disciplined rather than dramatic. Aura has announced a definitive agreement to acquire Newco, and that agreement would internalize mining fleet ownership and related operations across three key assets. The potential investor implication is improved control and operating leverage. The financial proof, however, will require details that have not yet been provided.
Aura Minerals’ October 2 announcement establishes the transaction’s scope, but not its valuation, funding structure, savings outlook or closing timetable. Until those data points emerge, the market is looking at a strategic operating move—not a quantified earnings event.
Bull/Bear Verdict
Bull Case: Bringing the fleet and heavy-equipment operations in-house across Apoena, Almas and Borborema may improve operating control, support margin leverage and strengthen future free cash flow if utilization and execution improve.
Bear Case: Without a disclosed transaction value, financing terms, projected savings or closing date, the deal’s effect on costs, margins and free cash flow remains uncertain, while Aura would assume greater responsibility for fleet ownership and operations.