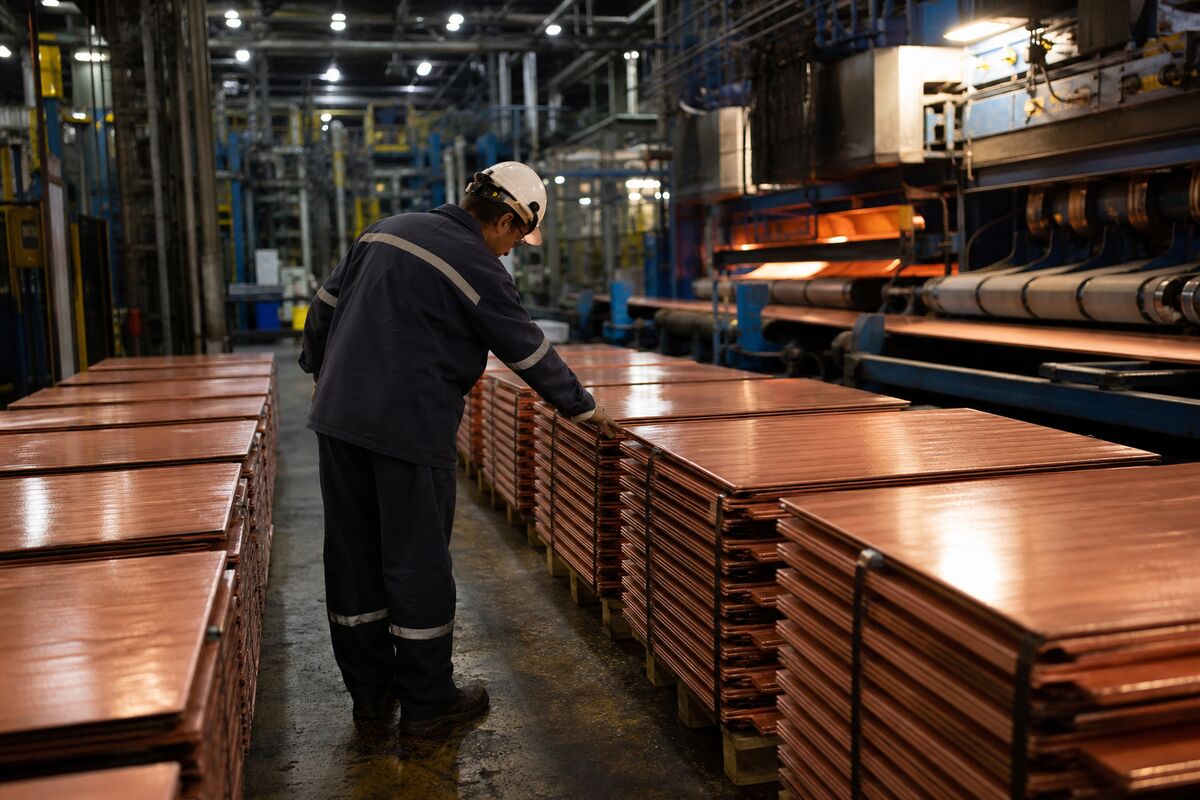
Copper’s rally has run into a political fog bank. Traders are growing more cautious as the market waits for clarity on potential U.S. tariffs, even while the physical supply outlook remains unusually tight. The result is a market pulled in two directions: bullish fundamentals underneath, tariff uncertainty overhead.
That tension matters far beyond the trading screen. Since President Trump returned to office, the prospect of U.S. trade measures has helped trigger a major reshuffling of global copper inventories. Metal has been moved, repositioned and reassessed as market participants try to anticipate how tariff policy could alter regional availability. The bull market may still have fuel, but traders are no longer treating the route ahead as a straight line.
The shift in sentiment is detailed in Bloomberg’s report on copper traders’ growing caution, which highlights the absence of clarity around potential U.S. tariffs. That uncertainty has become a market force in its own right. Even before a policy is finalized, the possibility of tariffs can change where copper is stored, how it is priced and how aggressively participants position in futures.
Inventories Become a Policy Chessboard
For copper futures, tariff risk is not merely a question of demand. It is also a question of geography. If traders expect the U.S. to impose tariffs, they may reassess the relative appeal of holding material in different regions. That can produce sharp inventory movements without necessarily changing the underlying amount of copper available worldwide.
This is why the inventory reshuffling since President Trump returned to office is so important. It suggests that the market is responding not only to mine output and industrial consumption, but also to the possibility that policy could redraw the flow of a globally traded metal. LME Copper sits at the center of that debate, with traders weighing visible inventory signals against an uncertain trade backdrop.
For investors tracking North American miners, smelters, materials producers and copper-linked ETFs, the message is similarly mixed. Tariff uncertainty may complicate regional pricing and supply assumptions, while tighter physical conditions could support the longer-term case for copper exposure. The assignment does not identify individual listed companies or ETFs, so the implications are sector-wide rather than tied to a specific ticker.
Tight Supply Keeps the Bull Case Alive
The tariff debate has not erased copper’s supply story. J.P. Morgan Global Research forecast copper at $14,800 per metric ton in the fourth quarter of 2026, citing tight mine supply and sulfur shortages. That figure is a forecast, not a reported market price or a guaranteed target. Its importance lies in what it says about the expected balance between future demand and the metal available to meet it.
Tight mine supply can make the copper market sensitive to even modest disruptions or delays. Sulfur shortages add another layer of pressure to the processing chain, potentially reinforcing concerns about the ability of smelters and other facilities to handle available material. Together, those factors help explain why the bullish outlook remains intact even as traders become less willing to chase the rally without clearer tariff signals.
The second source, a report on copper pressure, tight supply and new drilling programs, underscores the competing forces facing the market. New drilling programs may point to efforts to address future supply needs, but they do not instantly resolve current mine tightness or the uncertainty surrounding trade policy.
Positioning Meets Patience
For copper futures and LME Copper, the immediate question is whether tariff uncertainty remains powerful enough to restrain positioning despite the supply deficit narrative. Traders may demand more evidence before extending bullish bets, particularly while the market lacks clarity on the timing and scope of any U.S. measures.
That does not automatically invalidate the bullish case. It does, however, make the path more fragile. Inventory movements driven by policy expectations can amplify regional distortions, while tight mine supply and sulfur shortages can keep the physical market firm. The copper story is therefore less a simple contest between bulls and bears than a tug of war between near-term politics and longer-term scarcity.
For North American materials investors, that tug of war may keep copper-linked assets highly sensitive to headlines. The $14,800-per-metric-ton forecast provides one marker for the bullish outlook, but it should be read as an estimate grounded in supply concerns—not as an actual current price or a promise of where the market must go. Until tariff policy becomes clearer, copper’s celebrated rally may continue with one hand on the throttle and the other hovering over the brake.
Bull/Bear Verdict
Bull Case: Tight mine supply and sulfur shortages support J.P. Morgan Global Research’s forecast of $14,800 per metric ton for fourth-quarter 2026, potentially keeping copper futures, LME Copper and related North American materials exposures supported.
Bear Case: Uncertainty over potential U.S. tariffs has already contributed to a major global inventory reshuffling and may keep traders cautious, limiting positioning even while the supply outlook remains tight.