Copper’s recent price weakness has not changed UBS’s core view: the bank favors a long position as the market moves toward increasingly tight supply. That stance rests on a measurable shift in the global balance, with projected deficits of 219,000 metric tons in 2026 and 379,000 tons in 2027.
The central question for investors is whether the dip reflects a temporary loss of momentum or an early warning of weaker economic activity. UBS’s analysis points to the former, but the bullish case still depends on supply disruptions persisting while copper demand remains sufficiently resilient.
According to UBS’s copper market view, the projected deficit is not merely a one-year imbalance. The shortfall is expected to widen by 160,000 metric tons between 2026 and 2027, a change that highlights the difficulty of restoring supply quickly when mine output disappoints or operations face disruptions.
Supply is becoming the key variable
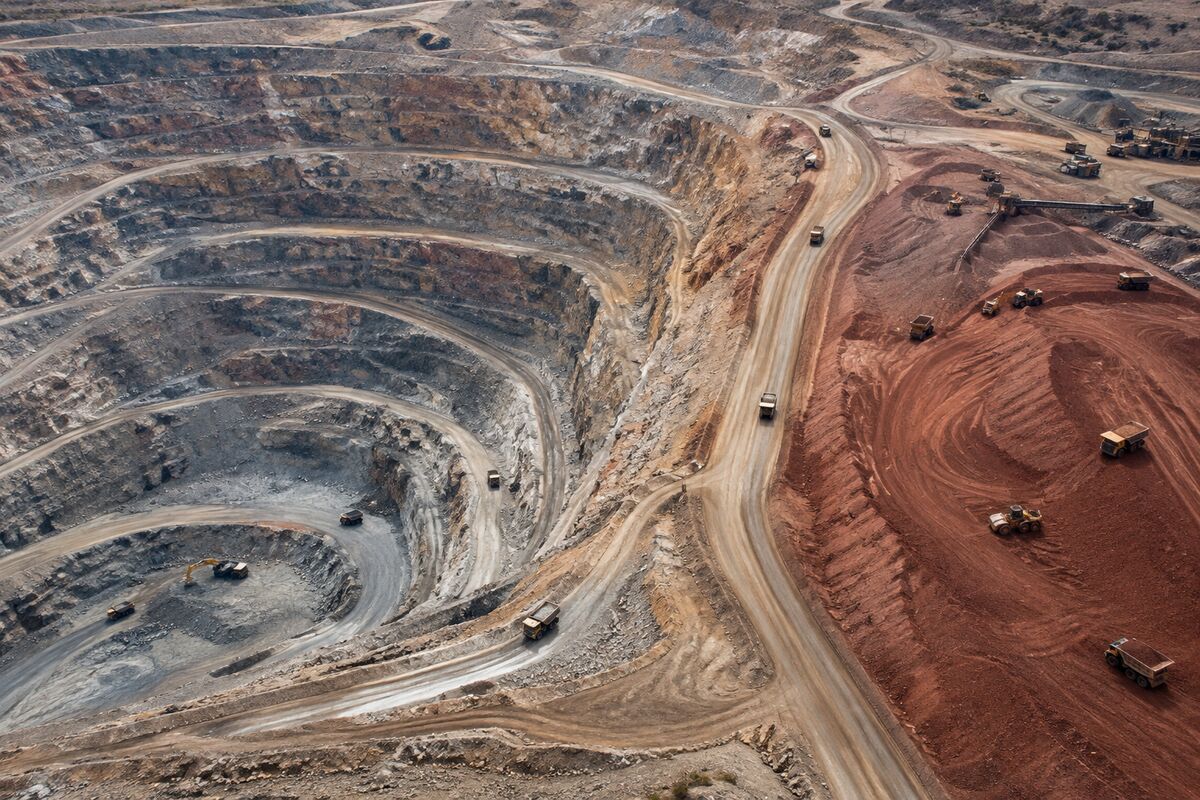
Mining disruptions and weaker production are cited as major drivers of the tightening outlook. For the copper market, that matters because new supply typically requires substantial development time, permitting, construction and operational execution. A short-term production setback can therefore have consequences beyond a single reporting period.
The projected figures create a clear data point for traders: 219,000 metric tons of deficit in 2026 could become 379,000 tons in 2027. That 73% increase, calculated from the supplied forecasts, suggests the expected gap is widening rather than stabilizing. It also means the market may become more sensitive to additional production problems.
Still, a widening projected deficit does not automatically translate into a straight-line rally. Copper remains exposed to the broader economic cycle. If economic activity weakens, demand could soften, potentially offsetting part of the bullish supply argument. Broader market volatility could also pressure commodities and mining equities even if the longer-term supply outlook remains constructive.
What the outlook means for North American miners
For US and Canadian copper producers, developers and exploration companies, a tighter global balance could improve the strategic value of future production. Established miners may receive greater market attention if supply disruptions continue. Developers could benefit from stronger interest in projects capable of adding future output, while exploration companies may attract attention as investors assess where the next sources of copper could come from.
That distinction is important. A projected deficit may support the sector’s long-term narrative, but it does not eliminate company-specific execution risks. Producers remain exposed to operational performance, developers face development and permitting hurdles, and explorers may not yet have producing assets. The same widening deficit can therefore affect different parts of the copper industry in very different ways.
Dip or warning signal?
UBS’s preference for a long copper position frames the recent weakness as potentially inconsistent with the longer-term supply-demand outlook. The 2026 and 2027 deficit estimates support that interpretation, particularly because the expected shortfall is widening alongside mining disruptions and weaker production.
But the counterargument is equally straightforward: copper demand is cyclical, and weaker economic activity could undermine near-term sentiment. For investors tracking North American copper equities, the most useful signal may be whether production problems continue while demand holds up—not simply whether the commodity has recently weakened.
The setup is therefore asymmetric in both directions. Persistent disruptions could reinforce the deficit case, while a sharper economic slowdown could delay its market impact. UBS’s bullish call provides a data-backed long-term thesis, but the path from projected shortage to stronger equity performance remains dependent on demand, execution and market conditions.
Bull/Bear Verdict
Bull Case: UBS’s long copper stance is supported by projected global deficits of 219,000 metric tons in 2026 and 379,000 tons in 2027, with disruptions and weaker production tightening expected supply.
Bear Case: Broader market volatility or weaker economic activity could reduce copper demand, limiting the near-term impact of the projected 73% increase in the deficit from 2026 to 2027.