The copper market has no shortage of development stories. What it has far fewer of are listed companies already producing metal. That distinction places Gunnison Copper in a different category from many Canadian-listed copper developers, even as the company reportedly explores a new stock market listing.
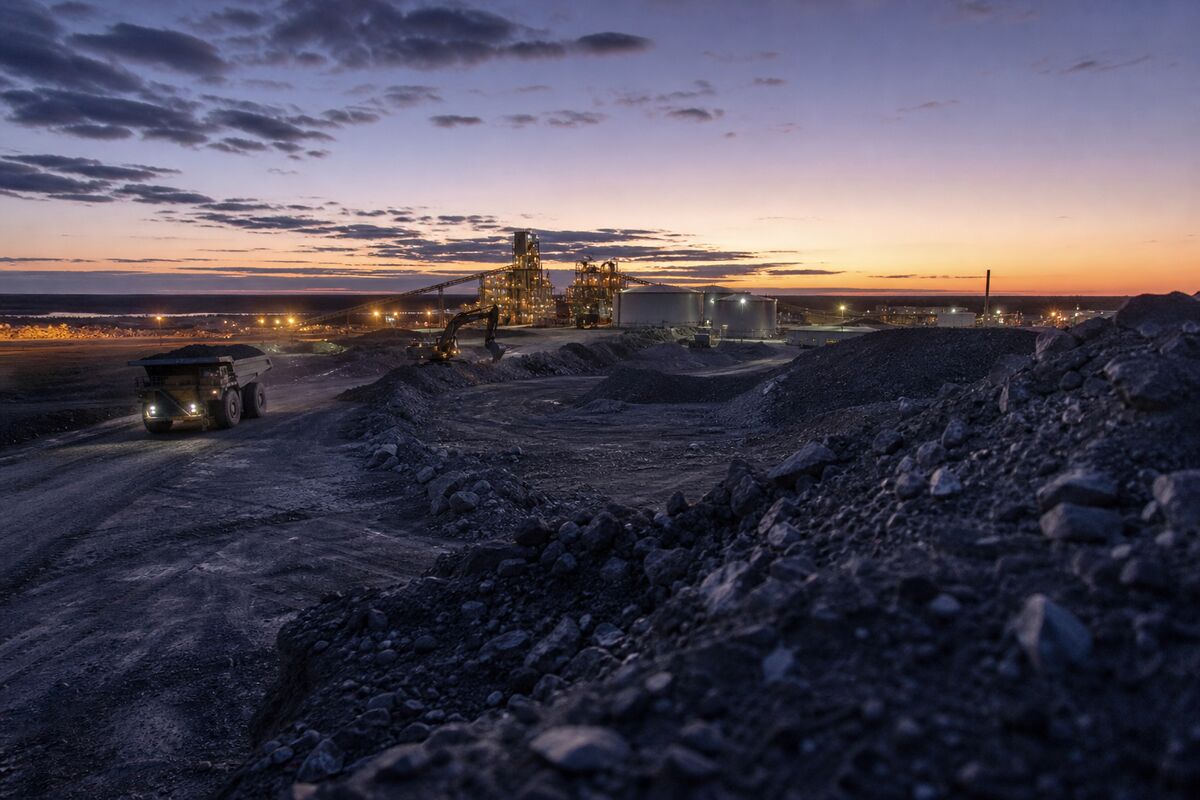
Gunnison Copper, listed on the TSX under $GCU (TSX:GCU), owns the Johnson Camp Mine in Arizona, which is already producing metal. If a new listing proceeds, the central question will not simply be where the shares trade. It will be whether broader market access helps investors recognize the difference between an operating copper asset and an exploration or development-stage project.
According to the source report, Gunnison Copper is reportedly considering a new stock market listing. That remains an exploration of corporate-market options, not a completed transaction. Investors should therefore separate the potential strategic rationale from any assumption that a listing will proceed or produce an immediate valuation benefit.
Why the listing question matters
A second or new exchange listing could matter because market access is part of the investment case. A broader listing may improve visibility among investors who do not routinely follow TSX-listed mining companies. It could also expand the shareholder base and, depending on participation and trading activity, potentially support greater liquidity.
Those outcomes are possibilities, not guarantees. A new listing would not automatically create demand, increase trading volume or change the underlying economics of the Johnson Camp Mine. The relevant point is that exchange access can influence how easily investors find, evaluate and trade a company. For Gunnison Copper, that question is particularly important because its operating status may appeal to investors seeking more direct exposure to copper production.
Production changes the comparison
Many copper companies listed in Canada remain at the exploration or development stage. Their investment cases may depend on further drilling, permitting, financing, construction or a future production decision. Gunnison Copper’s Johnson Camp Mine offers a different starting point: the project is already producing metal.
That does not eliminate operational or market uncertainty, and the assignment does not provide production volumes, financial results or a forecast for future output. It does, however, create a meaningful distinction in how the company may be assessed. Investors can examine Gunnison Copper through the lens of an operating copper asset rather than viewing it solely as a future mine concept.
That distinction may become more relevant as investors focus on potential copper supply shortfalls and seek exposure to operating assets. The market’s interest in copper is not limited to exploration success. It also extends to companies with assets that are already producing, although the source information does not establish that Gunnison Copper will increase production or that its valuation will rise.
Strategic backing adds context
The Johnson Camp project is funded by Nuton LLC, a venture tied to a global mining major. That backing is relevant because it gives the project an association with a larger mining-industry platform. The available information does not provide additional terms or establish what that relationship means for future financing, operations or corporate strategy, so investors should avoid reading more into it than the source supports.
Still, the combination of an operating Arizona mine, Nuton LLC funding and a potential new listing gives Gunnison Copper a profile that differs from a typical early-stage copper developer. The proposed market-access strategy may be intended to bring that profile to a wider investor audience.
The bottom line
Gunnison Copper’s potential listing is worth watching because it could affect visibility, liquidity and the composition of its shareholder base. The stronger argument, however, is the asset itself: Johnson Camp is already producing metal. Whether the market ultimately assigns greater value to that operating status will depend on execution, trading interest and the details of any listing—none of which are confirmed in the available information.
Bull/Bear Verdict
Bull Case: A new listing could broaden Gunnison Copper’s shareholder base and improve market visibility, while the producing Johnson Camp Mine may distinguish $GCU from exploration-stage copper developers.
Bear Case: The listing remains unconfirmed, and there is no sourced evidence that it would improve liquidity or valuation; the available information also provides no production increase or financial forecast.