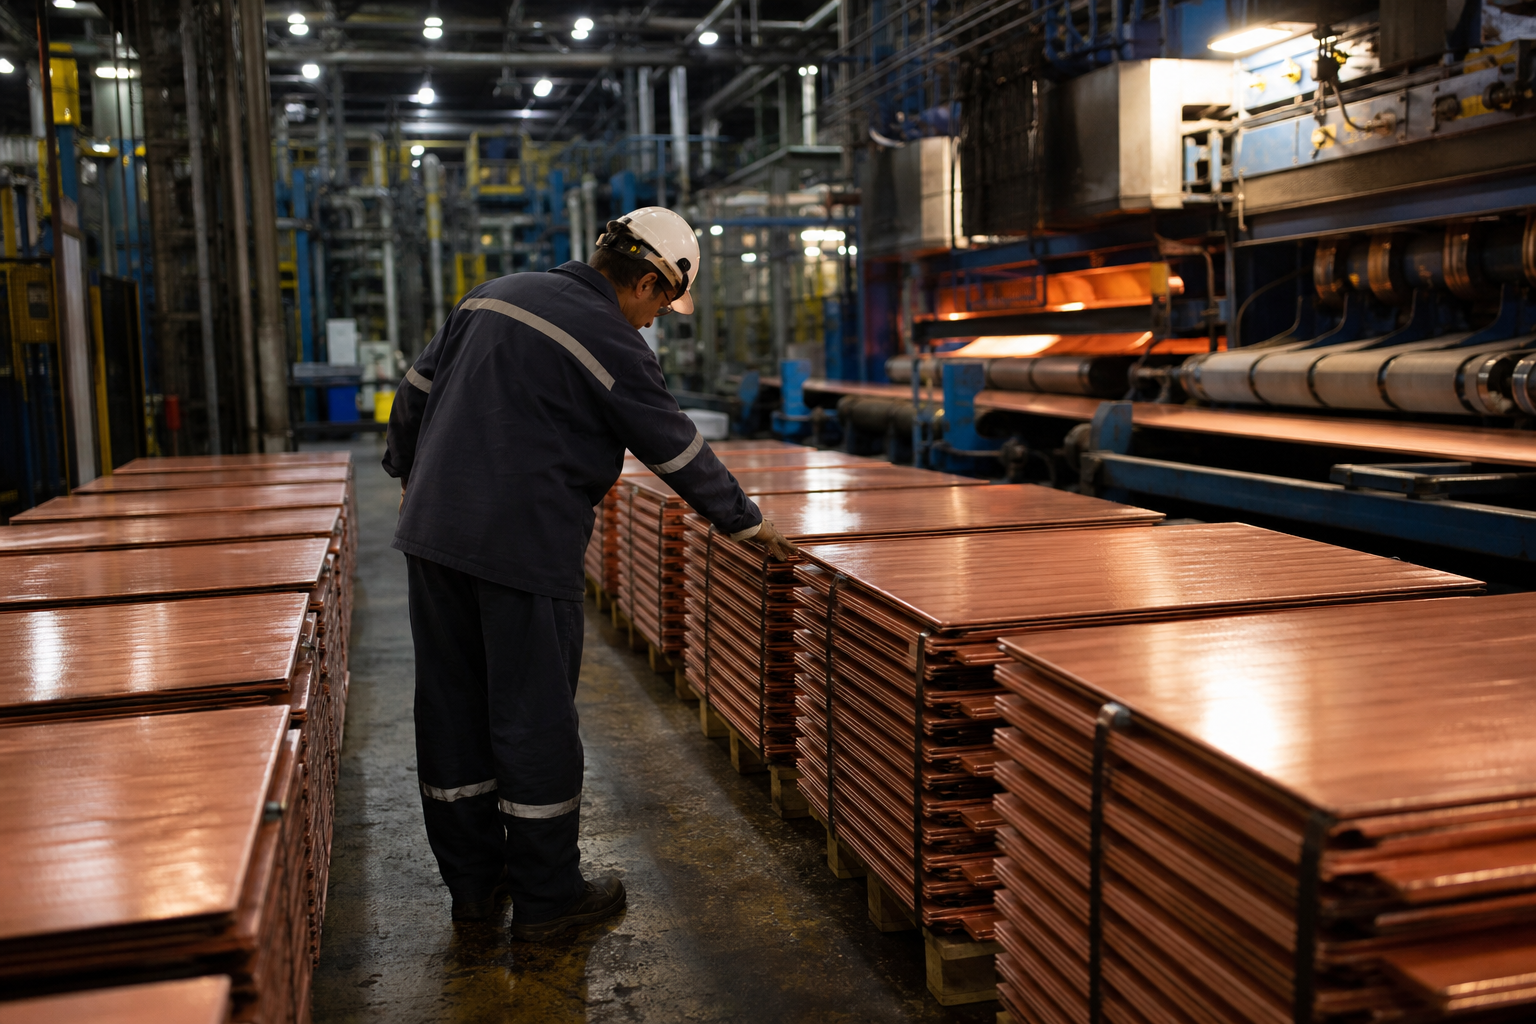
The world is witnessing a slow-motion train wreck in the copper market, where geopolitical tensions between the US and China are not just a backdrop but a driving force. As we delve into the intricacies of this intricate supply chain, the figures tell a stark story: global copper production has slipped by 1.1% in the first half of 2026, suggesting a potential annual downturn. This isn’t just a blip; it could spell trouble ahead for investors eyeing copper-focused mining stocks.
As the rivalry between these economic giants intensifies, the implications for copper supply chains are profound. Investments are flooding into African rail corridors, aiming to bolster infrastructure and secure resources. Yet, the projected supply deficit of 6.5 million tonnes by 2035 looms large, adding a sense of urgency to the conversation. For investors in the copper mining sector, the message is clear: the time to act may be now, as the stakes grow higher in this critical minerals landscape.
Declining Production: A Red Flag
The decline in global copper production is not merely an isolated incident; it’s symptomatic of larger structural issues within the market. A 1.1% drop in production during the first half of 2026 indicates that the industry could face significant challenges ahead. Mining companies are grappling with rising costs, regulatory hurdles, and the impacts of climate change, all of which may hinder their ability to ramp up production to meet future demand.
The Geopolitical Chess Game
The intricate ballet of US-China relations adds a layer of complexity to the copper supply narrative. As both nations seek to solidify their positions in the global economy, Africa’s rich mineral wealth has become a prized target. The US is making strategic investments in rail corridors across the continent, aiming to secure access to crucial resources, including copper. This geopolitical maneuvering heightens the stakes for copper supply chains, as both nations vie for dominance.
Supply Deficit on the Horizon
Experts are sounding the alarm bells about a looming copper supply deficit, projected to reach a staggering 6.5 million tonnes by 2035. This deficit is not just a number; it reflects the urgent need for increased investment in mining and infrastructure. With the demand for copper expected to surge due to its essential role in renewable energy technologies and electric vehicles, the market must brace itself for potential shortages.
Investor Implications
For investors, the current climate could present both challenges and opportunities. The declining production figures combined with geopolitical tensions suggest that copper-focused mining stocks may experience volatility. However, this volatility could also mean significant upside potential for those willing to navigate the shifting landscape. Companies with strong fundamentals and strategic positioning could thrive as the market adjusts to these emerging realities.
As the narrative unfolds, it’s crucial for investors to remain informed about the underlying factors driving these trends. The intersection of geopolitics and commodity markets is a complex web, and understanding its nuances may provide valuable insights for positioning within the copper sector.
In conclusion, the copper market stands at a critical juncture, with declining production, geopolitical tensions, and a looming supply deficit all converging to create an environment ripe for scrutiny. As the world moves toward a more electrified future, the demand for copper will only intensify, making it essential for stakeholders to keep a close watch on this pivotal mineral.
For a deeper dive into the implications of these trends, check out the analysis from Skillings Mining Intelligence and Discovery Alert.