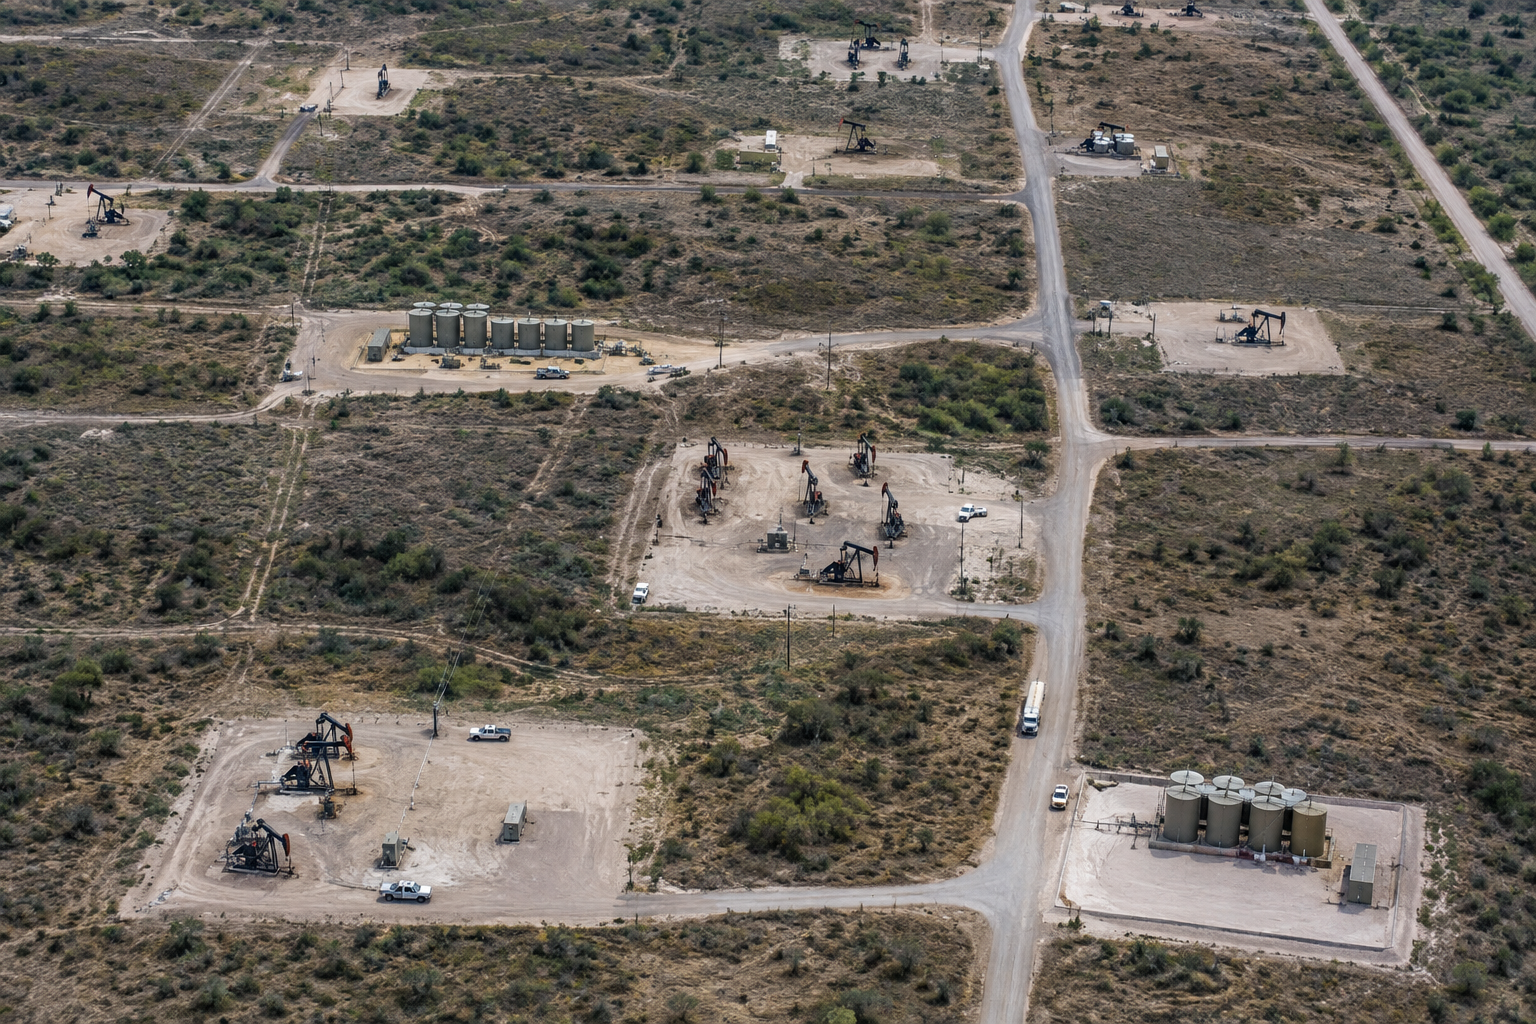
Crescent Energy has agreed to acquire Devon Energy’s Eagle Ford assets in a proposed $4.2 billion transaction, putting one of the most closely watched US shale basins at the center of another major portfolio reshuffle. Reported by Seeking Alpha on October 8, 2026, the deal gives the US energy market a fresh example of how exploration and production companies are repositioning around core assets.
The headline is simple, but the strategic message is larger: Crescent Energy is seeking to expand its position through a substantial Eagle Ford acquisition, while Devon Energy is choosing to part with a central US asset base. That is the kind of transaction that can say as much about corporate priorities as it does about geology or commodity prices.
The Eagle Ford is the fulcrum of the proposed deal. Rather than a scattered collection of properties, the transaction is explicitly centered on Devon’s Eagle Ford assets, giving the basin a starring role in the next chapter of US energy consolidation. For Crescent, the acquisition could represent a material change in the scale and shape of its portfolio. For Devon shareholders, the sale could mark an equally significant shift in how the company’s US production assets are organized.
Neither side’s move exists in a vacuum. The transaction was reported against a backdrop of higher oil prices linked to Middle East tensions and risks surrounding shipping through the Strait of Hormuz. That context may be relevant to how investors interpret the timing, but it does not establish the deal’s financial outlook or provide a forecast for either company. The reported transaction terms remain the $4.2 billion purchase price and the Eagle Ford asset focus.
A portfolio reshuffle, not just a headline deal
For Crescent Energy, buying the assets could signal a preference for concentrating capital in a known US producing region rather than building exposure through a broader collection of properties. The size of the transaction makes it a meaningful portfolio decision, with the Eagle Ford becoming the central lens through which investors may assess the company’s next phase.
For Devon Energy, selling the assets could indicate a desire to streamline its holdings or redirect attention elsewhere in its portfolio. The available information does not specify what Devon may do next, so the broader implication is best framed as a change in asset ownership rather than a confirmed new strategy.
That distinction matters for shareholders. A large acquisition can alter Crescent’s operating profile and the way the market views its growth ambitions. A major divestment can likewise change how Devon is assessed, even before investors know how the company intends to deploy the proceeds or reshape its remaining assets. Those questions remain open based on the reported details.
Another signal from US shale
The proposed transaction also fits a wider pattern of consolidation and asset optimization among US exploration and production companies. In a mature shale market, scale and basin focus can become increasingly important as companies evaluate which properties best fit their portfolios. The Crescent-Devon agreement suggests that high-value assets may continue moving between operators as management teams refine their US strategies.
Still, consolidation is not automatically a verdict for either company. The $4.2 billion price tag establishes the scale of the bet, while the Eagle Ford focus identifies where that bet is being made. Investors may now look for further information about the transaction before drawing conclusions about its ultimate impact.
Seeking Alpha’s October 8 report places Crescent Energy’s purchase of Devon Energy’s Eagle Ford assets at the intersection of portfolio strategy, basin consolidation and a tense commodity-market backdrop. The deal may become an important marker for US energy M&A—but its lasting significance will depend on how each company’s reshaped portfolio performs over time.
Bull/Bear Verdict
Bull Case: The proposed $4.2 billion acquisition could strengthen Crescent Energy’s position in the Eagle Ford and give the company greater scale in a basin central to the transaction.
Bear Case: The $4.2 billion price tag represents a substantial portfolio commitment for Crescent, while Devon’s sale leaves shareholders to assess the implications of a material change in its US asset base.
Source: Seeking Alpha