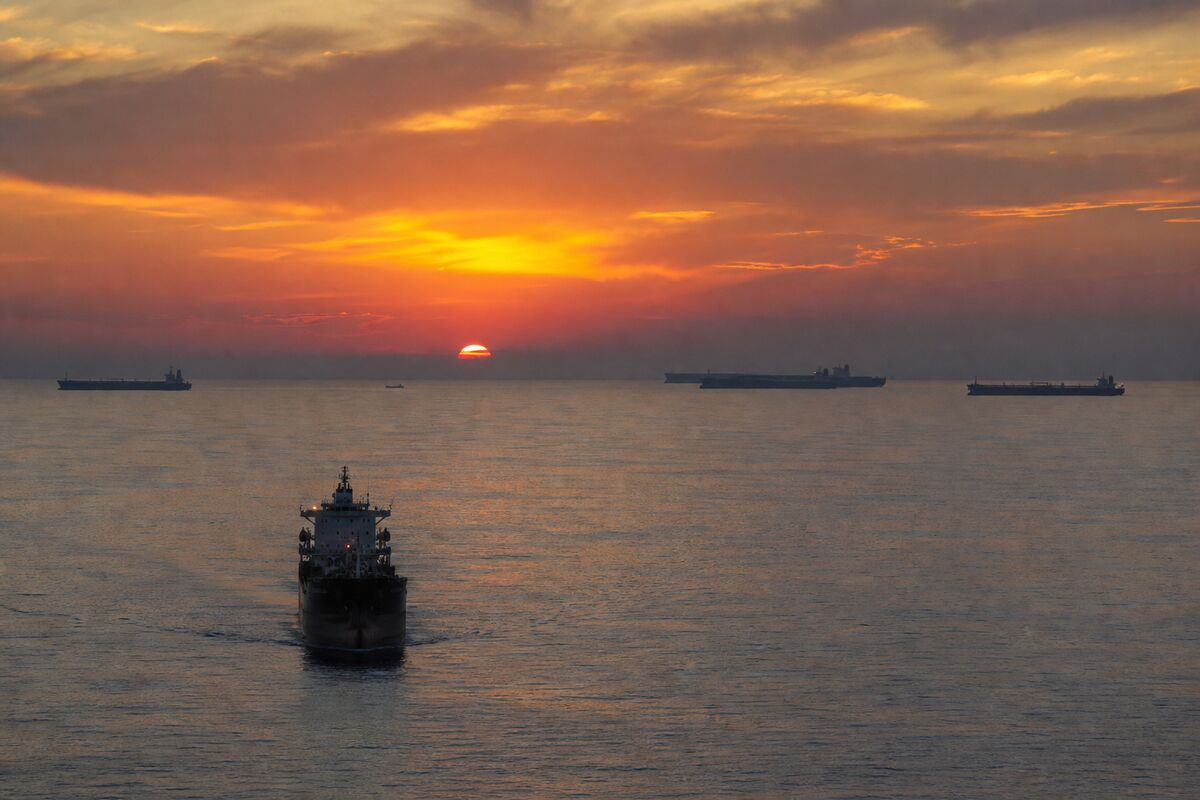
Oil’s latest rally has turned a narrow maritime passage into a broad North American market concern. Crude oil jumped 2% and settled at six-month highs as fears of escalation involving Iran added a fresh geopolitical risk premium to energy markets.
The immediate question for US and Canadian investors is not simply how high crude can go, but how long the market must price the possibility of disruption through the Strait of Hormuz. Reports of tanker incidents have put supply security, inflation expectations and central-bank policy back in the same conversation.
According to the reported account of the market move, security sources said a tanker in the Strait of Hormuz was hit by limpet mines. Iran’s IRGC Navy, meanwhile, stated that four tankers caught fire in the strait. Those claims are being attributed to the sources and military body involved; they should not be treated here as independently verified developments.
The distinction matters because markets can move sharply on the possibility of supply trouble before physical disruptions are fully established. Hormuz is therefore acting as more than a geographic reference. It is becoming a live test of how quickly traders attach a premium to crude when shipping security appears uncertain.
Supply risk meets a steady OPEC+ target
Reuters-cited sources reportedly said OPEC+ is set to keep oil output targets steady. That detail gives the market a second variable to weigh: if disruption fears intensify while formal production targets remain unchanged, crude pricing may be driven increasingly by the threat of lost or delayed supply rather than by a newly announced reduction.
A sustained disruption risk could keep the geopolitical premium elevated. If the reports fade without a broader interruption, some of that premium could retreat. If tensions escalate, however, the market may continue to price additional uncertainty into crude oil futures, even before the scale of any physical supply impact is clear.
What it means for US and Canadian energy markets
For North American energy producers, higher crude prices could improve the market backdrop for revenue expectations and support energy-equity valuations, although the effect would depend on how durable the move proves to be. The assignment identifies crude oil futures as the relevant market instrument; no individual US or Canadian energy company is named here.
The refining picture is less straightforward. Higher crude prices raise a refiner’s primary input cost. Refining economics could remain supportive if fuel prices adjust alongside crude, but margins may face pressure if product prices do not keep pace. That divergence could leave producers and refiners responding to the same headline in very different ways.
For investors watching US and Canadian markets, the distinction between a brief price shock and a sustained supply threat is central. A two-percent jump and a settlement at six-month highs establish a meaningful market reaction, but they do not by themselves establish the duration of the move or the eventual effect on company valuations.
The inflation and Federal Reserve channel
Crude is also an inflation story. If higher oil prices persist, they could lift inflation expectations by raising transportation and energy costs. That may complicate the Federal Reserve’s policy calculations: a sustained energy shock could make policymakers more cautious about easing financial conditions, while a short-lived move might prove less consequential.
That is an implication, not a forecast. The current information confirms a sharp market response and reports of tanker fires and an alleged limpet-mine attack, but it does not establish a confirmed, extended supply interruption. The Federal Reserve’s eventual response would depend on the persistence and breadth of any inflation effect, as well as other economic data not provided in this report.
The market’s next act may therefore hinge on verification and duration. If the Strait of Hormuz remains calm, the geopolitical premium could deflate. If reported incidents become part of a wider escalation, crude oil futures could retain the spotlight—and North American energy, refining and monetary-policy expectations could remain caught in its beam.
Bull/Bear Verdict
Bull Case: Crude’s 2% jump to six-month highs, combined with reported tanker incidents and steady OPEC+ output targets, could support North American energy-equity valuations if disruption fears persist.
Bear Case: If the reported claims are not followed by a sustained supply interruption, the geopolitical premium could fade, while higher crude costs could pressure refiners and complicate inflation expectations for the Federal Reserve.